Affordable health care should not depend on the size of someone’s paycheck or their address. Back in 2017, the legislature passed a “reinsurance” bill as a temporary fix to address the rising costs of health care. This legislation essentially sent a chunk of the budget surplus we had two years ago – $142 million – and $400 million from the Health Care Access Fund directly to insurers as an inducement for insurance companies to lower rates in the individual, non-group health care market.
To be fair, health insurance rates did even-out in some cases. However, when reinsurance passed two years ago, it was billed as a temporary emergency stop gap until a more permanent solution was found. Instead of exploring a more permanent solution, the Minnesota Senate on Monday, March 11, advanced a proposal to continue subsidizing health insurance companies for three more years. The proposal would maintain the reinsurance program, which allows the state to absorb some of the expenses private health insurers incur to offset the cost of care for some of the pricier claims they cover.
What started off as a temporary patch is now an expensive program that is becoming a long-term funding tool to keep Minnesota’s insurance market afloat. The reinsurance give-away hands insurance companies hundreds of millions of dollars, and continuing it is an irresponsible waste of taxpayer money.
We are throwing money at a problem without having any guarantees of or movement toward a long-term solution that will stabilize the individual market. It’s another “fix” that gives money directly to insurance companies without holding them accountable for how the funds are dispersed. Insurers on the individual market would see millions of dollars in costs removed from their books — and, theoretically, they would lower their prices to compensate. But there are no reform measures that provide information or ways to make sure the savings are passed on to consumers.
What really sets me off is that reinsurance takes funding from the Health Care Access Fund, which is intended to support health care for low-income Minnesotans to help insurance companies. We are basically taking funds from an insurance plan covering low-income people to subsidize multi-millionaire insurance companies and their executives. It’s ironic that the top-paid executives in Minnesota almost all come from the health care insurance industry; we know UnitedHealth Group’s CEO made $27 million last year, and 31 other health care executives earned more than $32 million collectively. Paying for a reinsurance program for insurance companies should not come at the expense of low-income Minnesotans.
There is no doubt that one of the reasons why Americans pay more for health insurance and health care than people in any other country in the world is because of high executive compensation. I have to ask: what is our moral obligation? Is it to fund wealthy health insurance CEO’s salaries or is it to ensure that those who most desperately need our limited health care resources receive it. Giving money directly to insurance companies should not come at the expense of providing the rest of our citizens’ health insurance coverage they can afford.
Supporters of reinsurance claim this program costs nothing because the legislature paid for it in 2017, but that’s simply not true. The bill costs Minnesota $77 million in federal funding for MinnesotaCare this year, creates a shortage in the Health Care Access Fund, and negatively affects MNsure’s budget. Minnesota needs real insurance reforms that offer some stability and improve access and affordability for Minnesotans. Continuing reinsurance is not that.
To contact me with your ideas and feedback, you can reach me by phone at 651-296-4154 or by email at sen.john.hoffman@senate.mn. You can also mail letters or pay me a visit in the Minnesota Senate Building, Room 2231, right across the street from the Capitol.
This column was first published in the Hometown Source.
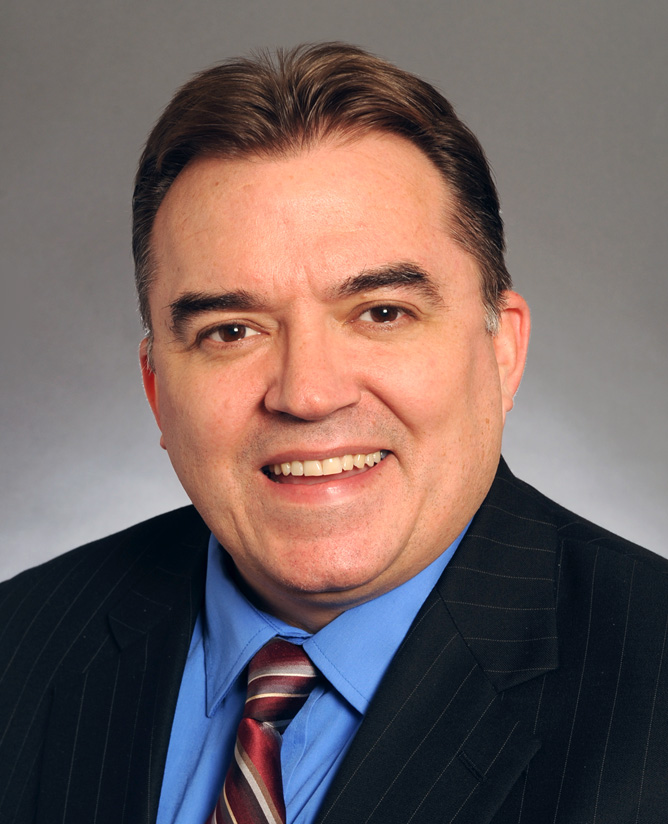
Learn more about Sen. Hoffman.
Read more news from Sen. Hoffman.


